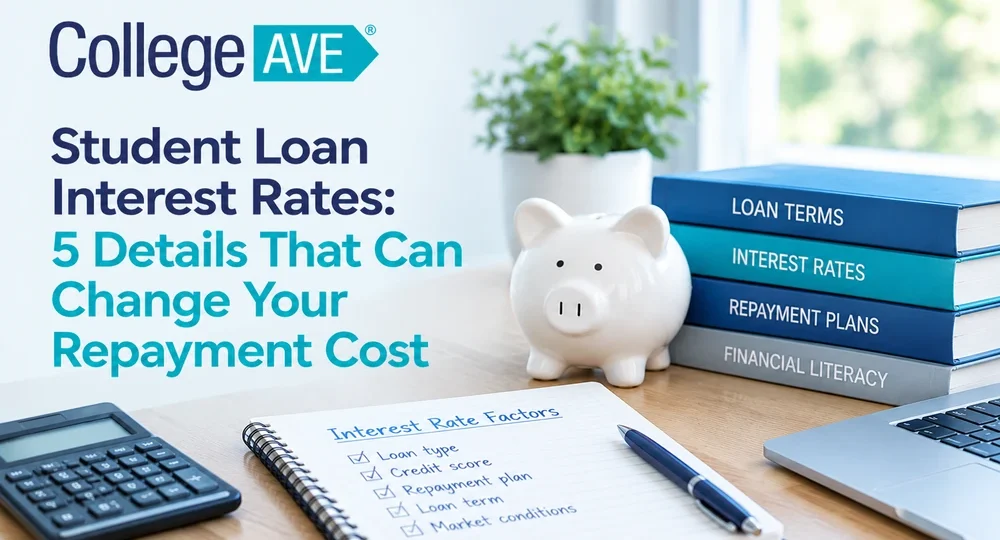
Student Loan Interest Rates: 5 Details That Can Change Your Repayment Cost
Getting a college loan is not simply a matter of obtaining enough money to fund the schooling. Your interest rate influences the monthly payments and the total amount that you pay back. Before jumping into a student loan, look at how the rate works so you understand what it means for your budget.
Some due diligence now can save you expensive and painful surprises down the line.
1. Fixed or Variable Interest Rate
A fixed-rate loan features an interest rate that never changes for the entire term of the loan. Hence allowing you to plan better for your monthly dues.
The rate that varies could increase or decrease over time. If the rate goes up, you could also see higher borrowing costs. Before taking out a private education loan, compare both types.
2. Look Beyond the Advertised Rate
Cost is broader than the interest rate and you have to cover this too. Third-party origination fees and other expenses attached to some loans can be expected. The final amount you pay is also determined by the repayment period.
A longer term tends to reduce your monthly payment. On the other hand, it may entail paying extra interest in perpetuity. Never look only at the monthly payment, always compare the total cost of borrowing.
3. Understand When Interest Starts
There are some loans that commence to generate interest even when you are in school. It can accrue, and if that interest remains unpaid it can cause an increase in the total amount you owe based on specific loan conditions.
It is important to look at your loan agreement and see when interest starts, how it calculates, and if unpaid, interest can be capitalized onto your balance.
4. Compare Your Options Carefully
Begin with understanding student loans interest rates and then learn how they will cost you in the long term. Then, shop around for rates with different lenders.
Review these details before signing:
The US has a fixed-rate section for all federal student loans (by law). They can be fixed or variable-based depending on the lender.
5. The Best Timeframe to Avoid Matching Your Loan to by Budget
Your initial salary may be lower than the amount you thought it would be. Look at how much you might earn after graduating and see if it compares favorably with what else you can expect to pay on your loan. Borrow only what you really need after accounting for grants, scholarships, and savings.
Make a Smarter Borrowing Choice
Student loans can help you afford to get a higher education but if you sign on for the wrong terms it could be niggling away at your finances for years. Be sure to read the contract agreement, overall cost, and ask questions before you invest. Having an ingrained repayment scheme helps manage the debt anxiety. Monitor your accrued loan information and review your budget periodically to catch any issues in advance. Once your financial circumstances change, get in touch with your loan servicer to find out what repayment choices you’ve got instead of lacking a fee.